Enterprise AI Agent Ambitions Are Running Far Ahead of Actual Deployments

Only 17 percent of organizations have agents deployed while more than 60 percent plan to within two years, the steepest ambition curve on the hype cycle.

If this caught your attention, that’s not accidental.

The best editorial systems don’t happen by accident. Outlever builds them.

Gartner's 2026 hype cycle delivered a diagnosis the agentic AI market needed to hear: the technology sits at the Peak of Inflated Expectations, with adoption ambition wildly outrunning adoption reality. Per the firm's CIO and Technology Executive Survey, only 17 percent of organizations have deployed AI agents to date, while more than 60 percent expect to within two years, the steepest intent curve of any emerging technology measured.
A 43-point gap between plans and production is not a pipeline. It is a warning.
What the 17 percent know
Gartner's own commentary explains the gap: most current deployments are narrowly scoped, and fully autonomous agents are not ready for the majority of enterprise use cases. The organizations actually in production got there by respecting that boundary rather than fighting it. They picked domains where the agent's job is definable, the data is reachable, the value lands on a revenue or cost line someone owns, and a human checkpoint exists for the moments that need one.
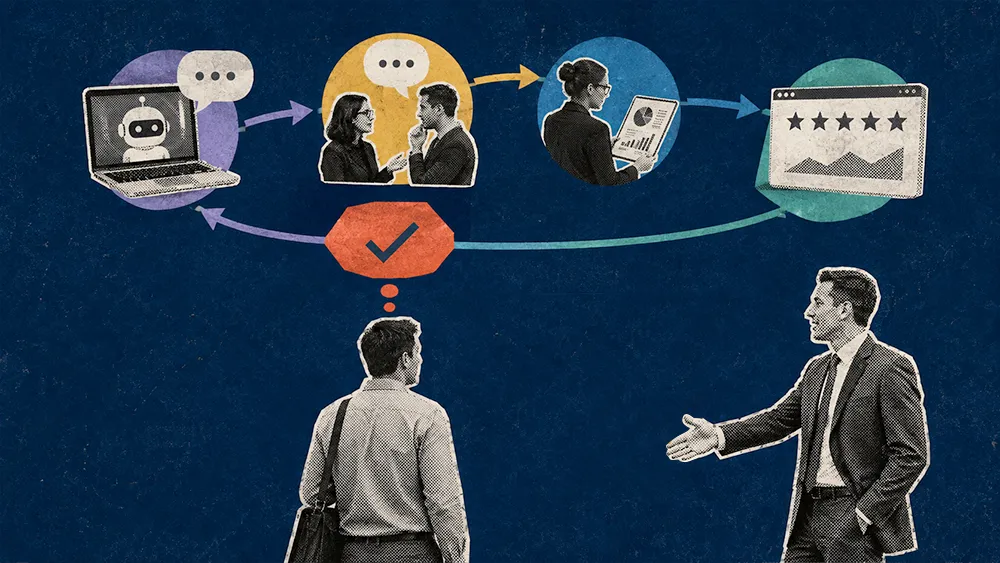
Customer-facing journeys keep showing up as the domain that fits. A buyer evaluation, an onboarding flow, a support resolution: each is a bounded conversation with a clear success state and an obvious escalation path to a person. Independent industry data corroborates the gap from another angle: one analysis found 79 percent of enterprises claiming to have adopted AI agents while only 11 percent run them in production, a spread that maps almost exactly onto Gartner's ambition curve. Adoption, in most of these organizations, means a pilot, a proof of concept, or a press release.
A second signal in the 2026 hype cycle deserves more attention than it has received: Gartner notes the emergence of governance, security, and cost-focused profiles alongside the core agent technologies, and the firm has forecast more than 2,000 legal claims tied to AI safety failures by the end of 2026. Translation: the market is learning, expensively, that an autonomous system without guardrails is a liability with an API. Governance capability is moving from a compliance checkbox to a first-order buying criterion, and vendors who treat it as an afterthought are self-identifying as members of the cancellation cohort.
Buying outcomes instead of ambitions
For the 60 percent with agents on the roadmap, the hype cycle placement is practical guidance, not an insult. Peak-of-expectations markets are where the gap between vendors is widest and hardest to see. Every deck promises autonomy. The differences live in the engineering layer buyers rarely inspect: how the system is evaluated, how it recovers from failure, how it is constrained, and whether the vendor's own team can explain the harness around the model rather than the model alone.
The enterprises that will look smart in 2028 are not the ones that moved first or the ones that waited longest. They are the ones that matched a real system to a real workflow with a real number attached, and treated everything else as theater. Seventeen percent have found that discipline. The other 43 points of ambition are about to discover whether they have it too.




Read what the room is reading.
New pieces for growth leaders, delivered as they publish. Unsubscribe whenever.